Excerpt from this week's: Technical Scoop: Gold Rebound, Lost Jobs, K Economy
Gold and silver
Source: www.stockcharts.com
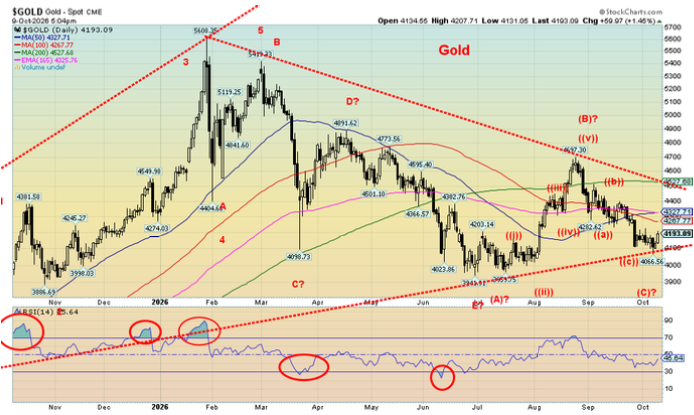
Despite a surging US$ Index, rising interest rates, and firm oil prices, gold rose this past week. Gold was up 1.3%, silver gained 0.6%, but platinum faltered, down 0.7%. Of the near precious metals, palladium fell almost 2.0% and hit 52-week lows. Copper rose 2.2%. The gold stocks caught a bit of a bid with the Gold Bugs Index (HUI) up 1.9% and the TSX Gold Index (TGD) rising 1.6%. Those are small but significant gains, given the dollar, interest rate strength, and oil firmness.
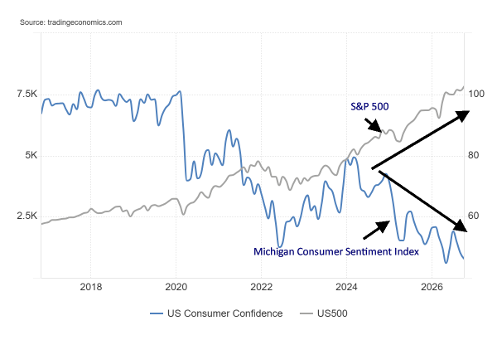
Gold may have gained a bit of confidence on expectations that the Fed won’t hike interest rates in October. Also, the Michigan Consumer Sentiment Index came in at a bearish 46.3, below the expected 47.6 and a reading of 48.1 in September. Consumer sentiment remains very low, seemingly in contrast to a stock market that is still making new all-time highs. The K economy? The Michigan Consumer Sentiment Index hit a record low in May at 44.8. The S&P 500 reached an all-time high this past week. The rich get richer. As for the rest – meh!
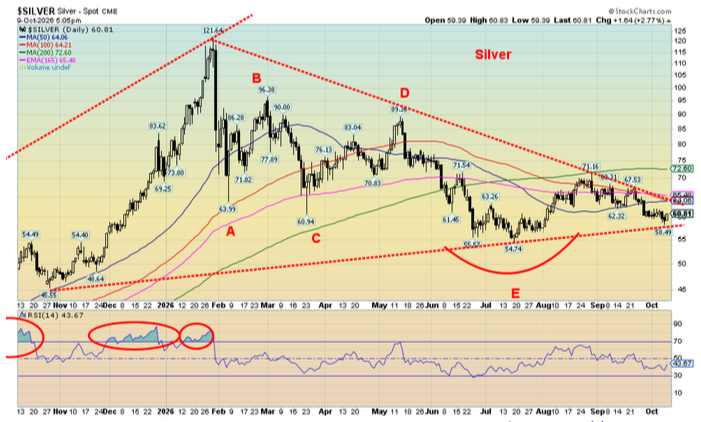
Gold sits on the cusp of either breaking down or surging higher. Unfortunately, the breakdown point is a lot closer than the breakout point. Gold breaks down under $4,100 but doesn’t break out until it is over $4,500. Silver is in the same conundrum as currently, at $60.81, the breakdown is under $58, but the breakout isn’t until over $66. We’d actually prefer it over $72 to feel confident.
The K Economy – S&P 500 vs. Michigan Consumer Sentiment Index 2016–2026
Source: www.tradingeconomics.com, www.umich.edu
We won’t get bullish until we take out our breakout points. We can’t ignore the breakdown points and recognize they remain at risk. But the rise in the face of dollar, interest rates, and oil this past week is encouraging.
Gold needs a black swan event. We watch the debt situation carefully as it is there that a potential black swan exists. A sovereign debt crisis? We already mentioned France. The Fed is not expected to act this month, but traders are still expecting another 25 bp rate hike by December. This week we get the inflation numbers. Any easing will help gold. But if they tick higher, then all bets are off. Irrespective of this, central banks continue to accumulate gold.
Another piece of encouragement came Friday when the gold stock indices (HUI, TGD) both gapped higher. A breakaway gap? The improvement for gold and the gold stocks was thanks to Trump announcing that he
wouldn’t hit Iran until after the mid-terms. That helped to steady oil and ease bond yields somewhat. But now Trump has threatened to hit the Houthis over the bombing of the Riyadh airport that killed 12 including an American citizen and injured over 300. Any entry of the U.S. into that war could trigger further expansion of an already dangerous and growing war. Impact on oil prices? TBD.
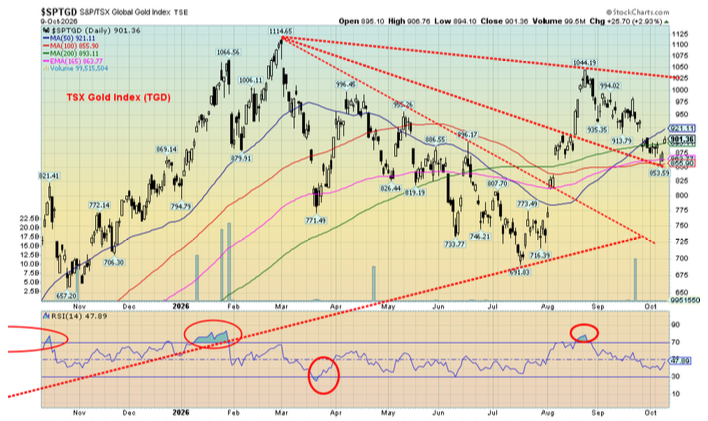
Upside follow-through for gold this coming week will be important. Falling back could signal new lows ahead. The TGD hit support near 865 and closed at 901. If there is any concern in the gold market, it is the feeble performance of the junior explorers. The TSX Venture Exchange (CDNX) fell again this past week, and many junior gold explorers are just moribund.
Source: www.stockcharts.com
Where we are encouraged about gold going forward is the stronger performance of the gold stocks vs. gold and silver and the strong performance of copper. Silver is down 50% from its all-time high in January 2026, gold is down 25%, but the HUI is off only 24% and the TGD is down 19% from the same point. Copper is up 1%, currently at $6.66 vs. $6.58 at the January 2026 high. The stocks and copper are usually the leaders. Normally, the stocks would be down 40%–60%, given the drops for gold and silver. But they aren’t. And copper is up, albeit a small rise.
As we noted, central banks continue to buy up some 170 metric tonnes in the first eight months. Leading the way have been Poland and China, both up roughly 80–100 tonnes. Their buying was offset by selling from Turkey and Russia, both unloading some 55–80 metric tonnes. Central banks bought 39 metric tonnes in August alone (source: World Gold Council www.gold.org).
Despite high prices, gold continues to be bought, particularly by Asian countries, but in North America gold is underowned.
Source: www.stockcharts.com
The case for gold remains as strong as ever, despite the setback and bear market of 2026. High interest rates, far too much debt, huge budget deficits, particularly for the G7 countries, and the shaky geopolitical situation are favourable for gold. Despite the weakness, the technicals continue to indicate some strength. We await the breakout.
A note on currencies as the US$ Index made 52-week highs this past week while the Cdn$ and the euro made 52-week lows. All the currencies were down this past week, except for the pound sterling which ended the week flat.
Read the FULL report here: Technical Scoop: Gold Rebound, Lost Jobs, K Economy
Copyright David Chapman 2026
Disclaimer
David Chapman is not a registered advisory service and is not an exempt market dealer (EMD) nor a licensed financial advisor. He does not and cannot give individualised market advice. David Chapman has worked in the financial industry for over 40 years including large financial corporations, banks, and investment dealers. The information in this newsletter is intended only for informational and educational purposes. It should not be construed as an offer, a solicitation of an offer or sale of any security. Every effort is made to provide accurate and complete information. However, we cannot guarantee that there will be no errors. We make no claims, promises or guarantees about the accuracy, completeness, or adequacy of the contents of this commentary and expressly disclaim liability for errors and omissions in the contents of this commentary. David Chapman will always use his best efforts to ensure the accuracy and timeliness of all information. The reader assumes all risk when trading in securities and David Chapman advises consulting a licensed professional financial advisor or portfolio manager such as Enriched Investing Incorporated before proceeding with any trade or idea presented in this newsletter. David Chapman may own shares in companies mentioned in this newsletter. Before making an investment, prospective investors should review each security’s offering documents which summarize the objectives, fees, expenses and associated risks. Although Artificial Intelligence (AI) may be deployed from time to time, AI output is monitored and adjusted, if necessary, for accuracy. David Chapman shares his ideas and opinions for informational and educational purposes only and expects the reader to perform due diligence before considering a position in any security. That includes consulting with your own licensed professional financial advisor such as Enriched Investing Incorporated. Performance is not guaranteed, values change frequently, and past performance may not be repeated.
About the author
Website: https://www.enrichedinvesting.com
Disclaimer: David Chapman is not a registered advisory service and is not an exempt market dealer (EMD) nor a licensed financial advisor. We do not and cannot give individualised market advice. David Chapman has worked in the financial industry for over 40 years including large financial corporations, banks, and investment dealers. The information in this newsletter is intended only for informational and educational purposes. It should not be considered a solicitation of an offer or sale of any security. The reader assumes all risk when trading in securities and David Chapman advises consulting a licensed professional financial advisor before proceeding with any trade or idea presented in this newsletter. David Chapman may own shares in companies mentioned in this newsletter. We share our ideas and opinions for informational and educational purposes only and expect the reader to perform due diligence before considering a position in any security. That includes consulting with your own licensed professional financial advisor.